Optimal control of fractional-order stochastic systems under uncertainty with Poisson and V-jump perturbations
Keywords:
Fractional systems, Uncertain–stochastic systems, Poisson jumps, V-jumps, Optimal controlAbstract
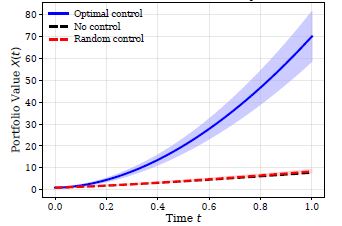
We address the optimal control problem for a novel class of fractional-order uncertain--stochastic dynamical systems perturbed simultaneously by stochastic and epistemic jump disturbances. The system dynamics are governed by Caputo fractional derivatives and driven by a multi-noise framework comprising Brownian motion, Poisson random measures, canonical Liu processes, and finite-variation uncertain V-jump processes, thereby establishing a hybrid fractional system with double-jump features. The primary novelty is a unified analytical framework that combines memory effects with dual-source jump discontinuities under probabilistic randomness and epistemic uncertainty. We prove the existence, uniqueness, and continuous dependence of mild solutions in a hybrid probability--belief L2 framework under standard Lipschitz and growth conditions. We then define an optimal control problem with a combined probabilistic--uncertain performance criterion, verify the existence of optimal controls, and derive a Pontryagin-type maximum principle using a backward fractional adjoint system. Finally, numerical simulations for a fractional portfolio optimisation problem demonstrate the practical implications of memory, control, and multiple-jump disruptions.
References
[1] I. Podlubny, Fractional differential equations, Academic Press, San Diego, USA, 1999. https://www.sciencedirect.com/book/9780125588409/fractional-differential-equations.
[2] A. A. Kilbas, H. M. Srivastava & J. J. Trujillo, Theory and applications of fractional differential equations, Elsevier, Amsterdam, The Netherlands, 2006. https://www.sciencedirect.com/book/9780444518323/theory-and-applications-of-fractional-differential-equations.
[3] M. Farman, ``Stability and chaos control of a fractional-order model for $mathrm{CO}_2$ emissions in the environment'', Modeling Earth Systems and Environment 11 (2025) 258. https://doi.org/10.1007/s40808-025-02429-5.
[4] S. Jamil, P. A. Naik, M. Farman & M. U. Saleem, ``Stability and complex dynamical analysis of COVID-19 epidemic model with non-singular kernel of Mittag-Leffler law'', Journal of Applied Mathematics and Computing 70 (2024) 3441. https://doi.org/10.1007/s12190-024-02105-4.
[5] F. Biagini, Y. Hu, B. O ksendal & T. Zhang, Stochastic calculus for fractional Brownian motion and applications, Springer, London, UK, 2008. https://doi.org/10.1007/978-1-84628-797-8.
[6] G. Di Nunno, B. O ksendal & F. Proske, Malliavin calculus for L'evy processes with applications to finance, Springer, Berlin, Germany, 2009. https://doi.org/10.1007/978-3-540-78572-9.
[7] B. Liu, Uncertainty theory, 2nd ed., Springer-Verlag, Berlin, Germany, 2007. https://doi.org/10.1007/978-3-540-73165-8.
[8] B. Liu, Uncertainty theory: a branch of mathematics for modeling human uncertainty, Springer, Berlin, Germany, 2010. https://doi.org/10.1007/978-3-642-13959-8.
[9] B. Liu, Uncertainty theory, 4th ed., Springer, Berlin, Germany, 2015. https://doi.org/10.1007/978-3-662-44354-5.
[10] X. Chen & B. Liu, ``Existence and uniqueness theorem for uncertain differential equations'', Fuzzy Optimization and Decision Making 9 (2010) 69. https://doi.org/10.1007/s10700-010-9073-2.
[11] K. Yao, J. Gao & Y. Gao, ``Some stability theorems of uncertain differential equation'', Fuzzy Optimization and Decision Making 12 (2013) 3. https://doi.org/10.1007/s10700-012-9139-4.
[12] K. Yao, ``Extreme values and integral of solution of uncertain differential equation'', Journal of Uncertainty Analysis and Applications 1 (2013) 2. https://doi.org/10.1186/2195-5468-1-2.
[13] K. Yao & X. Li, ``Uncertain alternating renewal process and its application'', IEEE Transactions on Fuzzy Systems 20 (2012) 1154. https://doi.org/10.1109/TFUZZ.2012.2194152.
[14] W. Fei, ``On existence and uniqueness of solutions to uncertain backward stochastic differential equations'', Applied Mathematics: A Journal of Chinese Universities 29 (2014) 53. https://doi.org/10.1007/s11766-014-3048-y.
[15] D. Applebaum, L'evy processes and stochastic calculus, 2nd ed., Cambridge University Press, Cambridge, UK, 2009. https://doi.org/10.1017/CBO9780511809781.
[16] N. Ikeda & S. Watanabe, Stochastic differential equations and diffusion processes, 2nd ed., Elsevier/North-Holland, Amsterdam, The Netherlands, 1989. https://www.sciencedirect.com/bookseries/north-holland-mathematical-library/vol/24.
[17] K. Yao, Uncertain renewal processes, Springer, Singapore, 2019. https://doi.org/10.1007/978-981-13-9345-7.
[18] F. Khan, A. Zehra, M. Farman, K. S. Nisar, A. Sambas & M. Hafez, ``Caputo gH-differentiability for Gronwalls inequality: insight, new results and application'', Journal of Inequalities and Applications 2025 (2025) 148. https://doi.org/10.1186/s13660-025-03395-3.
[19] P. A. Bankole, M. E. Adeosun, S. E. Fadugba, T. Fadina & C. Thron, ``Existence and uniqueness results for double jump fractional uncertain differential equations'', Journal of the Nigerian Society of Physical Sciences 8 (2026) 3153. https://doi.org/10.46481/jnsps.2026.3153.
[20] P. A. Bankole, M. Nasir & S. Etemad, ``Operator-theoretic probability framework in Morrey spaces with applications to option price dynamics'', Journal of Mathematics 2026 (2026) 9834733. https://doi.org/10.1155/jom/9834733.
[21] A. Ahmad, M. Farman, A. Ghafar, M. Inc, M. O. Ahmad & N. Sene, ``Analysis and simulation of fractional order smoking epidemic model'', Computational and Mathematical Methods in Medicine 2022 (2022) 9683187. https://doi.org/10.1155/2022/9683187.
[22] N. T. Danat, F. A. Abdullah, M. K. M. Ali, M. O. Adewole & J. Andrawus, ``Onchocerciasis control via Caputo-Fabrizio fractional dynamics: a focus on early treatment and vector management strategies'', Journal of the Nigerian Society of Physical Sciences 8 (2026) 2942. https://doi.org/10.46481/jnsps.2026.2942.
[23] X. Chen & D. A. Ralescu, ``Liu process and uncertain calculus'', Journal of Uncertainty Analysis and Applications 1 (2013) 3. https://doi.org/10.1186/2195-5468-1-3.
[24] W. Ma, L. Liu & X. Zhang, ``Stability in $p$-th moment for uncertain differential equation with jumps'', Journal of Intelligent & Fuzzy Systems 33 (2017) 1375. https://doi.org/10.3233/JIFS-17332.
[25] Z. Jia, X. Liu & C. Li, ``Existence, uniqueness, and stability of uncertain delay differential equations with V-jump'', Advances in Difference Equations 2020 (2020) 440. https://doi.org/10.1186/s13662-020-02895-4.
[26] Z. Gao, X. Wang & M. Ha, ``Multi-asset option pricing in an uncertain financial market with jump risk'', Journal of Uncertainty Analysis and Applications 4 (2016) 1. https://doi.org/10.1186/s40467-015-0043-7.
Published
How to Cite
Issue
Section
Copyright (c) 2026 Philip Ajibola Bankole, Sunday Emmanuel Fadugba, Mabel Eruore Adeosun, Malesela C. Kekana (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.